Are Your Payments Driving Growth? Get Your Free Growth Index Score

Building Payments Around the Way Construction Actually Works

Read time: 3 minutes 

Construction doesn’t bill like other industries.

Work may be completed over months or years. Billing follows project progress rather than a traditional point of sale. Payment applications build on previous billing periods. Retainage may hold back a portion of earned revenue. Change orders can alter contract value. Stored materials may need to be accounted for before they’re installed.

For the software platforms serving contractors, those aren’t minor industry details. They’re part of the workflows customers expect their technology to understand.

And they have an important implication for embedded payments: a construction payment experience can’t be designed separately from the construction workflow around it.

In construction, getting paid starts long before the payment

A typical commercial construction billing cycle involves much more than generating an invoice.

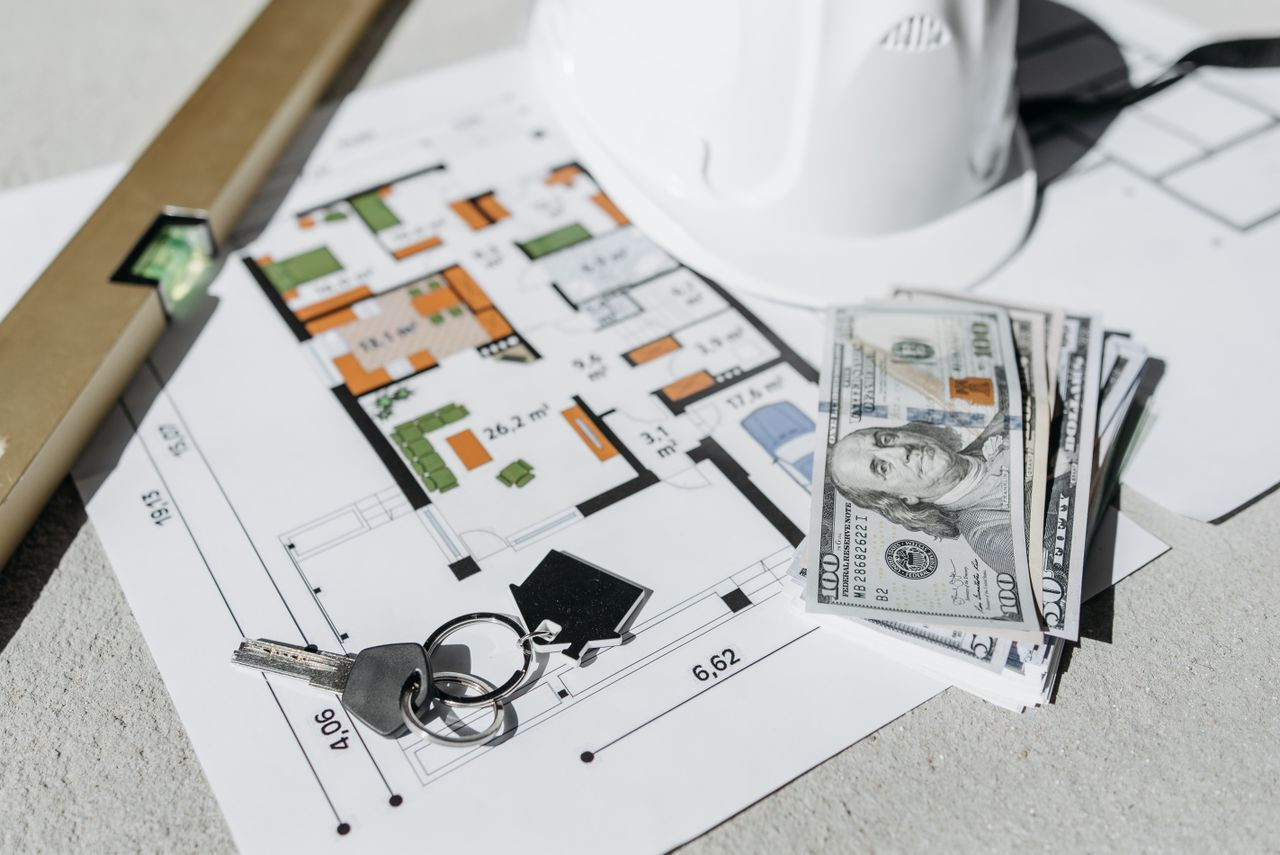
Progress billing often starts with a schedule of values (SOV) that breaks the contract into billable components. As work progresses, contractors submit pay applications reflecting work completed during the billing period, prior billings, stored materials, and the amount currently due.

Depending on the project, that process may also involve AIA-style G702/G703 documentation, percent complete, retainage, approved change orders, lien waivers and multiple layers of review and approval. Current construction software products increasingly bring these elements together as one connected billing workflow.

That’s why a generic invoice-to-payment experience only tells part of the story.

The software platform has to understand what happened before a customer is ready to pay—and what needs to happen afterward to keep the project and financial records aligned.

Retainage and progress billing change the payment experience

Take retainage.

A portion of payment may be withheld until contractual conditions are met or the project reaches a later stage. That means the amount earned, the amount billed and the amount actually paid aren’t necessarily the same.

Progress billing creates another layer. Each new pay application may depend on the original contract value, the schedule of values, prior applications, work completed during the current period, stored materials, retainage and approved changes.

For a construction software company, those mechanics matter because customers don’t experience “billing,” “payments,” “project management” and “accounting” as completely separate worlds.

They’re parts of the same project lifecycle.

The opportunity for construction software platforms is bigger than payment acceptance

This is where embedded payments can become strategically interesting for an ISV.

The goal isn’t simply to give contractors another way to accept a card or ACH payment.

It’s to make the payment experience feel like a natural continuation of the project and billing workflows the platform already manages.

For the software provider, that can create value in several ways.

A stronger product experience. Customers can complete more of the project-to-cash workflow without leaving the software.

Greater platform relevance. Connecting project activity, billing, and payments can make the platform more central to the financial side of the job.

Product differentiation. Construction software that understands how the industry actually bills can deliver a more relevant experience than a generic payment capability bolted onto the product.

A path to platform growth. When payments happen within the software, the ISV has an opportunity to participate in payment activity that may otherwise happen through disconnected providers. For example, Concrete Pumping Holdings, the nation’s largest concrete pumping company, offers a look at what that depth of participation can mean. Centralizing payment activity across nearly 95 branches in 23 states, with data flowing nightly into their accounting system for reconciliation, solved exactly the kind of visibility and workflow challenges an ISV’s own customers deal with every day.

The construction workflow becomes the context. The stronger software platform is the outcome.

Don’t force construction workflows into a generic payments model

This is where the payments partner matters.

Construction software companies shouldn’t have to simplify the way their customers work simply because a payment provider was designed around a conventional checkout experience.

A better approach starts with questions such as:

  • How does the platform already handle progress billing?
  • Where do pay applications and approvals happen?
  • How are invoices, project records, and incoming payments connected?
  • What role do retainage and change orders play in the customer experience?
  • Where can payments be introduced without creating another disconnected process?

Those are software-platform questions as much as payments questions.

And they require a partner that understands the vertical—not just the transaction.

Build around the way construction gets paid

Construction software earns its place in the market by understanding the complexity that generic business software doesn’t.

Payments should follow the same principle.

When payment capabilities are designed around project-based billing and connected to the workflows contractors already use, the software platform can provide a more complete experience while strengthening its own value proposition.

The goal isn’t to turn a construction ISV into a payments company.

It’s to help the platform do more for the construction businesses that already depend on it.

For a deeper look at how software platforms can approach embedded payments, explore our Embedded Payments That Strengthen Your Platform guide, including how to evaluate ownership models, adoption strategy, platform value, and the role of a strategic payments partner.

Ready to get started? Contact us, and we’ll walk you through the next steps.
Building a Stronger Manufacturing Platform With Embedded Payments

Read time: 3 minutes 

For manufacturers, a payment rarely stands on its own.

It sits at the end of a much longer operational chain: an order is entered, inventory is allocated, materials move, production happens, goods ship, an invoice is generated, and eventually payment needs to be collected and reconciled.

Manufacturing software platforms already sit at the center of much of that activity. The opportunity with embedded payments is to bring another critical part of the customer workflow into the same experience.

For ISVs serving manufacturers, that makes payments more than an additional feature. Done well, embedded payments can make the platform more useful to customers, create a more connected experience, and give the software provider a greater role in the workflows that drive its customers’ businesses.

Manufacturing workflows don’t end at the invoice

Manufacturing software is built around interconnected processes.

Sales orders affect inventory. Inventory availability influences production planning. Production and fulfillment lead to shipment. Shipment triggers invoicing. And ultimately, incoming payment has to be associated with the right customer, invoice, and business record.

That interconnectedness is why payments shouldn’t be treated as an isolated transaction at the edge of the platform.

Manufacturing systems commonly connect workflows across orders, inventory, production, dispatch, invoicing, and finance. Industry software providers themselves increasingly describe these processes in terms such as quote-to-cash, order-to-cash, procure-to-pay, production planning and inventory management.

When payment happens through a disconnected experience, customers may be forced to move outside the system they use to run the rest of the business.

For the software platform, that’s a missed opportunity to make the product more complete.

Embedded payments should fit the way manufacturers already work

Embedding payments isn’t simply about placing a payment button inside an application.

The more important question is whether payments fit naturally into the workflows the platform already supports.

A manufacturing customer may need to accept ACH or commercial card payments against an invoice, manage payment terms across business customers, identify incoming payments, and reconcile those payments back to the appropriate records.

The exact requirements vary by manufacturer and software platform. But the principle is consistent: the payments experience should adapt to the business workflow rather than forcing the business workflow to adapt to payments.

That’s particularly important in B2B environments, where the transaction is often only one step in a larger financial and operational process.

A stronger payments experience can make the platform stronger

For manufacturing ISVs, the strategic opportunity isn’t simply to help customers accept another form of payment.

It’s to ask what role payments should play in the broader platform strategy.

There are several ways to think about that value.

A more connected customer experience. When payments live closer to invoicing and the other workflows customers already manage in the platform, users have fewer reasons to move between disconnected systems.

Greater product value. Extending the workflow through payment can make the platform more central to how customers run their businesses.

New revenue opportunities. Payment activity already taking place across the customer base may create an additional opportunity for platform monetization.

More differentiation. For software providers competing in specialized manufacturing markets, an embedded payments strategy designed around real manufacturing workflows can become part of the product experience rather than a generic add-on.

That changes the strategic question from “Should we add payments?” to “How can payments make our platform more valuable?”

Integration is only the beginning

The technical integration matters, but getting payments live isn’t the same thing as building a successful payments program.

Software platforms also need to think about how customers discover the capability, how they activate it, how it fits into existing workflows and what will drive adoption over time.

That makes the right payments relationship important beyond APIs and processing.

An embedded payments partner should understand the B2B environment the ISV serves, help the platform determine how much of the payments experience it wants to own, and support the program as it moves from integration to activation, adoption and growth.

Build payments around the platform you’re already building

Manufacturing ISVs don’t need to become payments companies to make payments a more valuable part of their product.

They need a strategy that recognizes the complexity of the manufacturing environment and connects payments to the workflows their customers already rely on.

When that happens, payments become more than the last step in a transaction. They become another way for the platform to create value for customers—and participate more deeply in the business activity it already supports.

 Want to explore what that could look like for your platform? Read our Embedded Payments That Strengthen Your Platform guide for a deeper look at ownership models, adoption, platform growth and what to evaluate in an embedded payments partner.

Ready to get started? Contact us, and we’ll walk you through the next steps.
Five Red Flags to Consider When Looking for a Sage 50 Payments Solution 

Running a business is all about efficiency. Sage 50 software allows businesses to streamline their accounting processes, capture more revenue, and remain compliant. A Sage 50 payment integration should be just as efficient and embed seamlessly into the software. The last thing you need is a payments solution that creates headaches instead of streamlining your workflow. 

That’s why it’s important to investigate each payment processing solution thoroughly. The integration you plug into your system should improve cash flow, automate manual processes, and ensure secure data compliance. 

But, as you know, not all payment solutions are created equal. So, in this blog, we cover five common red flags to be wary of when considering a Sage 50 payments solution. 

Red Flag #1: Long-term contracts 

Don’t get locked in. While a long partnership is ideal, you don’t want to be stuck with an ill-fitted solution. Longer commitments make it difficult for merchants and organizations to negotiate terms and fees.  

Pay-as-you-go, no contract solutions exist, and they are often preferable.  

Red Flag #2: Non-PCI compliant solutions 

Any payment solution you use should be PCI-compliant – end of story. Sensitive customer data is involved when accepting payments, and you don’t want to leave yourself open to liabilities. Even more, non-compliance fees can drain your financial reserves, with penalties as high as $10,000 a month.   

Red Flag #3: Manual payment collection 

Your integration should never require you to chase down customer payments. Constant follow-up on unpaid customer invoices drains your time, cash, and resources. The right payment processor should have the right tools in place to combat this. 

Tools like click-to-pay invoicing embed payment links in emails and text messages to streamline payments. Other solutions like autopay create automated follow-ups and recurring payment options.  

Red Flag #4: Non-customizable solutions

Payments isn’t a “one-size-fits-all” industry, and most businesses need to tweak their payment solution to match their strategy. A best-in-class payment processor should have deep, dynamic APIs that promote customization. APIs should be user-friendly, comprehensive, and have ongoing developer documentation. 

Red Flag #5: Non-certified Sage Solution

Finally, most important of all, your payment solution should be Sage certified. As a Sage 50 user, you want to ensure your payment solution has been vetted by the program itself. If a payment solution isn’t loudly proclaiming its certified status, it’s best to turn the other way.  

Transform Your Sage Payments with a Certified Solution 

With its award-winning APIs and detailed developer documentation, Fortis is a leader in Sage integrations. Being both a Plus Tier Sage Tech Partner and Sage Recommended Solution, our team of seasoned experts and developers deliver a best-in-class Sage 50 integration to streamline payment processing.  

Fortis has no red flags. Enjoy features like: 

  • Click-to-pay invoicing 
  • Level 2 and 3 data enrichment 
  • Next-day funding 
  • Acceptance of all payment types 
  • Flexible pricing options 
  • And, a dedicated ERP support team 

Discover the Fortis difference, yourself. Contact us today or check out our integration in the Sage Marketplace.  

QuickBooks Users: How a Best-in-Class Integration Boosts Your Cash Flow 

Every business owner knows the struggle of chasing down payments from customers. It disrupts your workflow, creates unnecessary stress, and can even hinder your ability to operate smoothly. So, what can you do to eliminate the struggle? 

The answer is simple – leverage a best-in-class payment integration. A best-in-class payment integration for your QuickBooks accounting software can not only help manage your cash flow, but also help improve your business’ operations. In this blog, we discuss the top three benefits of choosing the right payment integration for QuickBooks. 

Benefit #1. Lower Your Costs: 

  • Reduced Fees: Forget those hefty processing fees that eat into your profits. Best-in-class integrations can secure you cheaper rates, including lower per-transaction costs. 
  • Surcharging Power: Offer customers the option to cover a small convenience fee for credit card payments. This allows you to offset processing costs and keep your margins healthy. 
  • Level Up Processing: Unlock the benefits of Level 2 and 3 processing by submitting additional data with each transaction. This can lead to even more significant reductions in processing fees. 

Benefit #2. Get Paid Faster with Streamlined Invoicing:

  • Digital Revolution: Ditch the paper chase! Modern integrations allow you to send invoices electronically via email or text message. This ensures faster delivery and eliminates the delays associated with snail mail. 
  • Autopay for the Win: Make life easier for your customers and yourself by offering them the option to set up automatic payments. This means you get paid on time, every time, with minimal effort. 
  • Transparent Communication: Clear and detailed invoices ensure your customers understand exactly what they owe, reducing confusion and encouraging prompt payment. 

Benefit #3. Embrace the Power of Payment Flexibility: 

  • Your customers have preferences. A best-in-class integration lets you safely accept a wide range of payment types, including credit cards, debit cards, ACH transfers and more. This allows customers to pay how they want, leading to a smoother checkout experience and higher sales conversions. 

QuickBooks Integration Made Easy: Streamline Your Business with Fortis 

Looking for a best-in-class integration that seamlessly connects with your accounting software? Look no further than Fortis! Our powerful solution integrates effortlessly with QuickBooks, allowing you to: 

  • Automate Tasks & Save Time: Say goodbye to manual data entry! Fortis automatically syncs transactions with QuickBooks, freeing you up to focus on strategic initiatives. 
  • Gain Real-time Insights: Access up-to-date financial data anytime, anywhere. This empowers you to make data-driven decisions and identify growth opportunities. 
  • Scale with Confidence: As your business grows, Fortis scales with you. Our robust platform can handle increasing transaction volumes without skipping a beat. 

Don’t just manage your cash flow, unlock your business’s full potential with Fortis and a seamless QuickBooks integration. For more information and to get started, visit our website.